-
Why SC
-
Aggressive incentives position industries for growth
-
-
Industries
-
View our thriving industries & vendors with the state
-
-
State Economy
-
-
International
-
Start Exporting
Expand to the US
Trade Policies
Contact our network around the globe
-
-
About
-
Our recruitment track record and awarded incentives
-
- Contact

Program Background
The Opportunity Zone (OZ) program is a federal initiative designed to encourage economic development and job creation through long-term private investment in designated low-income urban and rural communities.
Originally enacted as part of the Tax Cuts and Jobs Act of 2017, the OZ program provides federal tax incentives for taxpayers who reinvest realized capital gains into Qualified Opportunity Funds (QOF), which in turn invest in designated Opportunity Zones.
Under the One Big Beautiful Bill Act (OBBBA) signed by President Trump—the Opportunity Zone program was made permanent and modernized to support long-term and targeted investment. Investors may benefit from the deferral of capital gains and additional tax advantages tied to the duration of their investment, encouraging sustained capital formation in underserved communities.
Opportunity Zones 2.0
The One, Big, Beautiful Bill Act (OBBBA) was signed into law on July 4, 2025, making the Opportunity Zone program permanent. Under the updated law, Opportunity Zones will be redesignated every 10 years, and several aspects of the program’s requirements and incentives have been revised.
As a result of these updated requirements, not all currently designated Opportunity Zones will qualify under the revised eligibility criteria. This places greater importance on the upcoming redesignation process as states identify priority areas for inclusion in the next round of designations.
Under federal guidance, governors are provided a window—beginning July 1, 2026—to submit Opportunity Zone nominations to the U.S. Department of the Treasury. This timeline shapes the state’s nomination process and requires timely coordination with local stakeholders to identify and advance priority census tracts.
Each governor is allowed to nominate up to 25% of the state's eligible census tracts for Opportunity Zone designation.
In an effort to support Governor McMaster in his efforts to ensure the state’s nominations reflect local priorities, SC Commerce will engage with local governments, economic development organizations, community leaders, and the public at large to provide input.
Census tracts selected
Governor McMaster submitted his nominations for Opportunity Zones to the US Treasury on September 23, 2026. A list can be found here. Once approved by the US Treasury, the new OZs will go into effect on January 1, 2027.
Changes Under OBBBA
The OBBBA introduces several updates to the Opportunity Zone program:
- Makes the Opportunity Zone program permanent and requires that OZs be redesignated every 10 years.
- Establishes new reporting requirements for Qualified Opportunity Funds and directs the U.S. Treasury to publish annual reports on Opportunity Zone investment activity and outcomes, increasing transparency around the program’s impact.
- Provides a new incentive structure, including a five-year rolling deferral beginning on the date of investment and a 10 percent step-up in basis for investments held for five years.
- Updates eligibility criteria by defining low-income communities as census tracts that meet either:
- A median family income below 70 percent of the applicable state or metropolitan median or
- A poverty rate of at least 20 percent and a median family income below 125 percent of the applicable median.
- Eliminates the “contiguous tracts” exception from the first iteration of the program.
- Updates eligibility criteria by defining low-income communities as census tracts that meet either:
- Enhances the incentive for investment in rural Opportunity Zones
- Defines a rural area as any area other than:
- A city or town with a population of greater than 50,000 and
- An urbanized area adjacent to a city or town with a population in excess of 50,000.
- Defines a rural area as any area other than:
NOTE: Review the IRS Notice 2025-50 for more information on the definition released by the U.S. Treasury.
- Provides a 30 percent step-up benefit for investments in a rural Opportunity Zone.
- Reduces the substantial improvement threshold for qualifying projects in rural Opportunity Zones from 100 to 50 percent.
Opportunity Zone Participation Overview
Opportunity Zones create a framework for businesses, communities and investors to work together to drive economic growth and unlock private capital.
*Some of the information below is subject to change pending future U.S. Treasury guidance.
For Businesses
To take advantage of the Qualified Opportunity Zone (QOZ) program, businesses must meet the following requirements.
-
Business Property
Substantially all (70%) of the business’ tangible property needs to be:
- Acquired after December 31, 2026, from an unrelated party.
- Used in any Opportunity Zone 70% or more of the time.
- Originally used or substantially improved within the Opportunity Zone.
-
Business Requirements
A QOZ Business must meet the following criteria:
- Earn 50% of its gross income from business activities within an Opportunity Zone.
- Use 40% or more of its intangible property in the active conduct of Opportunity Zone business.
- Not hold non-qualified financial property.
- Operate a qualified business, which includes most activities except for golf courses, country clubs, gambling establishments, etc.
-
Other Considerations
Businesses will also need to evaluate the following when considering investing in QOZs:
- If seeking an outside investor, is the business willing to give up equity?
- Is the business likely to grow significantly and generate additional gains over the next 10 years?
- Is the business likely to remain in a qualified Opportunity Zone for the next 10+ years?
For Communities
States and local communities can use Opportunity Zones to attract private investment without new public spending, catalyze redevelopment in distressed or underutilized areas, support job creation and tax base growth, and complement existing incentives to improve overall competitiveness. Communities should follow this process to attract investment.
-
South Carolina QOZ Participation Process
- Participate in the Opportunity Zone nominating process to recommend census tracts in your market.
- Work to engage investors to attract targeted projects to your community.
- Structure deals in a way to benefit the community, QOFs and QOZ businesses.
For Investors
Investors do not need to live, work, or operate a business in an Opportunity Zone to invest in South Carolina. Review the criteria below to understand the requirements of participating through a Qualified Opportunity Fund (QOF).
-
QOFs Definition
A Qualified Opportunity Fund (QOF) specializes in attracting investors with similar risk and reward profiles to collect and place capital in rural and low-income urban communities. QOFs are corporations or partnerships structured specifically to deploy capital into QOZs.
-
Gain Deferral Qualification
To create a Qualified Opportunity Fund (QOF), businesses or individuals with realized capital gains must invest gains within 180 days into a QOF. Then, the QOF has six months to invest 90% of the funds in a qualified Opportunity Zone property or business.
-
Business Requirements
Qualified Opportunity Funds (QOFs) must meet the following criteria:
- Must be funded by private capital and guided by market principles.
- Must invest 90% of their assets in Opportunity Zone assets.
- Can only invest in Opportunity Zones via stock, partnership interests or business property.
- Assets must be to create new business activity or substantially improve existing business.
- If improving an existing business, the QOF must double the investment basis over 30 months.
- Qualified activities include creating new businesses, new real estate or infrastructure.
- Disqualified activities include golf courses, country clubs, gambling establishments, etc.
-
Other Considerations
Investors will also need to evaluate the following when considering a QOF investment:
- Assets must be held for at least 10 years to realize full benefits. Can the investor manage the liquidity risks?
- Does the investor have an exit strategy if the desire is to sell the business and realize the gain deferral on the sale of the assets?
Upcoming & Recent Engagement Opportunities
RECORDING | Webinar: Opportunity Zone Program and Nomination Process, May 2026
Watch webinar recording from May 21, 2026 to learn more about updated eligibility requirements, program benefits and the process to recommend census tracts.
How Opportunity Zones Work
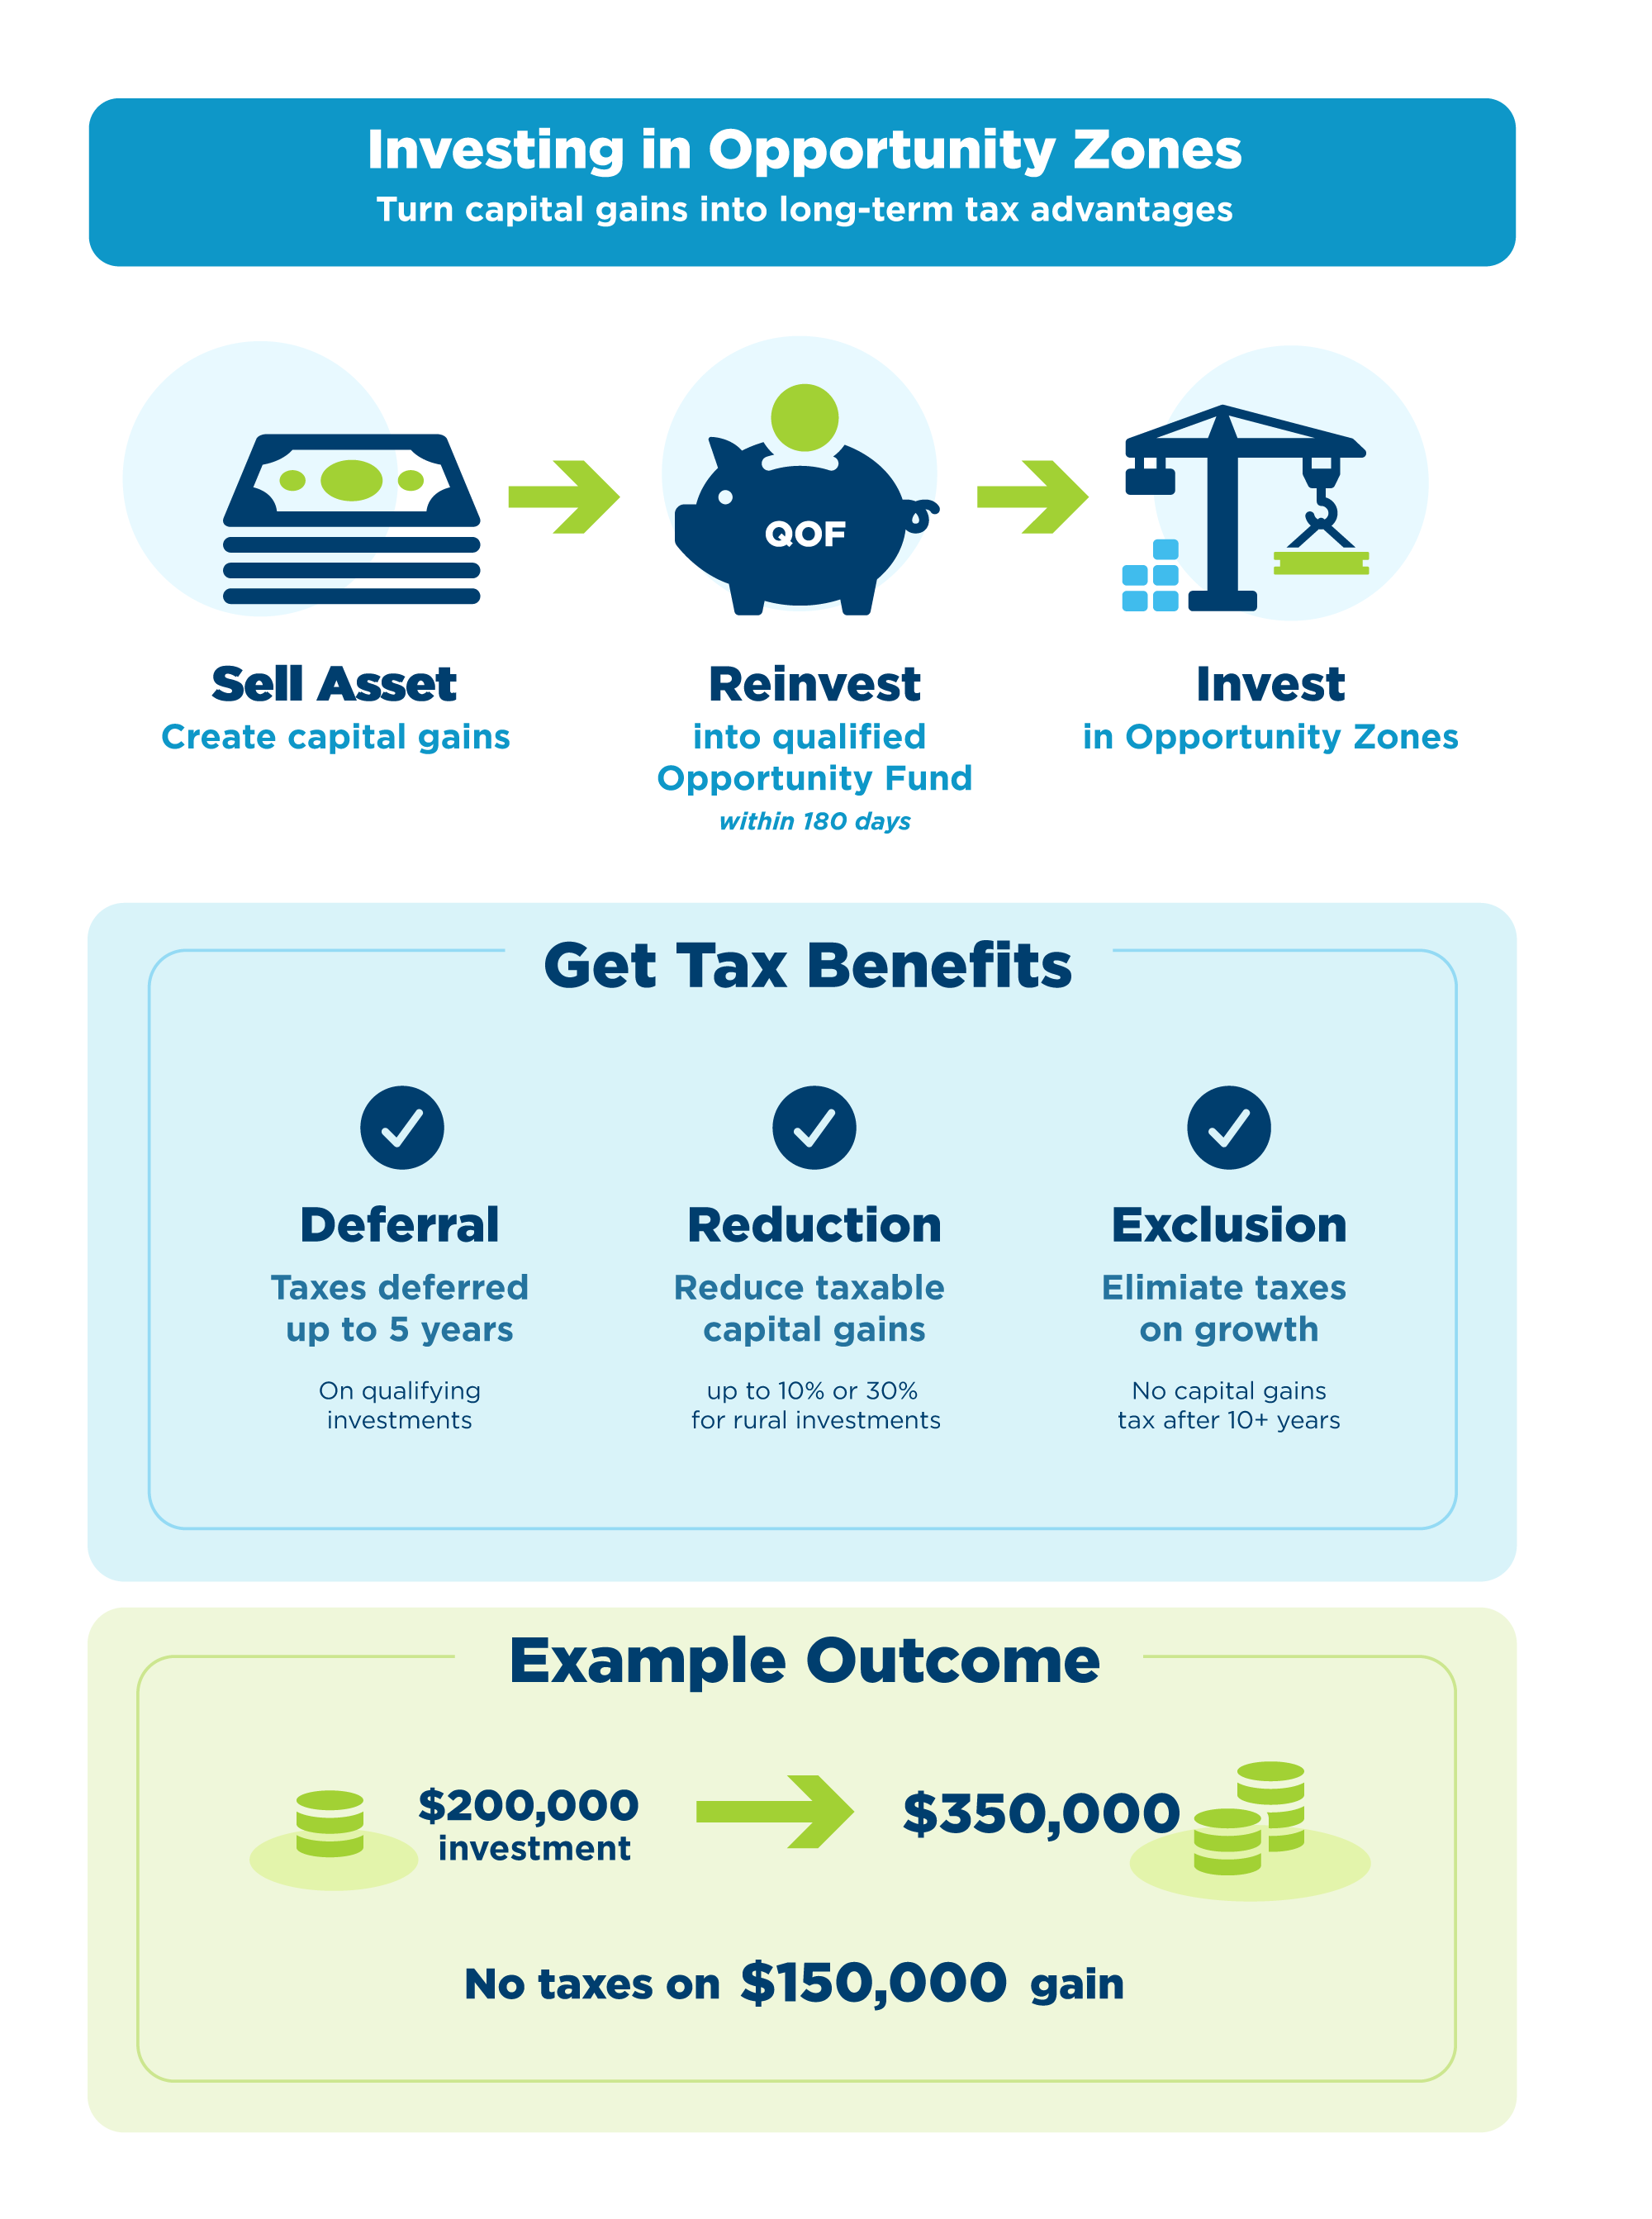
- Step 1: Create Capital Gains: An investor sells assets (stocks, real estate) and generates a capital gain.
- Step 2: Reinvest in Fund: Within 180 days, the investor places the gains into a Qualified Opportunity Fund (QOF).
- Step 3: Invest in Zones: The QOF invests in Qualified Opportunity Zone property, businesses, or real estate (e.g., affordable housing, business development).
- Step 4: Tax Benefits under Opportunity Zone 2.0:
- Deferral: For gains invested in QOF after December 31, 2026, taxes are deferred until 5 years after the investment in QOF.
- Reduction of Deferred Gains: The adjusted basis of any QOF investment held for at least 5 years is increased by an amount equal to 10% of the deferred gain, or 30% for investments made into rural QOF investments
- Exclusion (10+ years): A taxpayer who holds its QOF investment for at least 10 years may elect, on the sale or exchange of the QOF investment, to adjust the tax basis of the disposed investment to (1) the FMV on the date of sale, or (2) the FMV on the 30th anniversary of the investment date (for investments sold after 30 years)
South Carolina Opportunity Zones Interactive Map
The map below shows census tracts eligible for consideration for Opportunity Zone designation as determined by the U.S. Treasury and nominated by Governor McMaster to be designated as Qualified Opportunity Zones. See https://www.irs.gov/pub/irs-drop/rp-26-14.pdf. Approved Opportunity Zones will go into effect January 1, 2027.
Click the map to open an interactive view of the opportunity zones submitted by Governor McMaster.
The map below reflects Opportunity Zone designations approved in 2018 and does not represent current or future designations. Areas marked in blue represent current Opportunity Zones that were designated in 2018 and will only be effective until the end of 2026. When using the search tool, you may need to zoom out to determine whether a location falls within a highlighted zone.
This map reflects Opportunity Zone designations approved in 2018 and does not represent current or future designations.
* This address locator is provided as a service to help potential investors determine the likelihood that a particular address falls within an Opportunity Zone. It is not meant to provide a definitive judgement on the qualification of a particular address and should not be used as such. It is advised that all prospective participants in the Opportunity Zone program consult the County of record for a more detailed analysis of the parcel in question as well as evaluate the regulations put forth by the U.S. Department of the Treasury.
Download a PDF of the 2018 Opportunity Zone census tracts (not current designations).
Opportunity Zone FAQs
-
What is the Opportunity Zone program?
The Opportunity Zone program is a federal tax incentive program designed to encourage long-term private investment in economically distressed areas.
-
Why was a tract eligible last time, but isn't eligible this time?
The definition of a low-income community has been narrowed, reducing the total number of tracts that meet the baseline criteria. Additionally, tracts that are not low-income communities but border a low-income community are no longer eligible for designation. See below for additional information:
Metric / Criteria QOZ 1.0 (2017 – 2028) QOZ 2.0 (2027 onward) Median Family Income (MFI) Tract MFI cannot exceed 80% of the statewide or metropolitan area median Tract MFI cannot exceed 70% of the statewide or metropolitan area median Poverty & Income Alternative Poverty rate of >= 20%, OR MFI does not exceed 125% of the area median Poverty rate of >= 20%, AND MFI does not exceed 125% of the area median Contiguous Tract Rule Allowed up to 5% of designated zones to be adjacent, higher-income tracts if contiguous to a true LIC Completely eliminated -
If currently designated, does it automatically become a new Qualified Opportunity Zone (QOZ) under the updated program?
No, a currently designated Qualified Opportunity Zone (QOZ) does not automatically become a new QOZ under the One Big Beautiful Bill Act (OBBBA). The OBBBA effectively resets the program, creating a second phase often referred to as "OZ 2.0." There is no grandfathering of existing designations. Each tract must be re-evaluated and re-nominated based on the new criteria.
-
Who selects the tracts?
The Governor may designate up to 25% of the eligible sites in the state subject to the approval of the United States Treasury. More information on the process is outlined in Rev. Proc. 2026-14, which can be found at https://www.irs.gov/pub/irs-drop/rp-26-14.pdf.
-
How many tracts are eligible in a county?
The number of tracts available in each county will be subject to the discretion of the Governor who may designate up to 25% of the eligible sites in the state.
-
Will all eligible tracts receive an Opportunity Zone designation?
No, OBBBA allows for 25% of eligible tracts to be nominated. The nomination process begins at the local level and then advances to the Governor's Office and S.C. Commerce for review.
-
Is it important to prioritize eligible census tracts when submitting recommendations?
Yes, this is very important. Locals know the tracts better than anyone else. Governor McMaster wants to consider the plans, strategies and priorities of local communities in making decisions.