Opportunity Zones
The Opportunity Zone (OZ) program is a federal initiative designed to encourage economic development and job creation through long-term private investment in designated low-income urban and rural communities.
Program background
Originally enacted as part of the Tax Cuts and Jobs Act of 2017, the OZ program provides federal tax incentives for taxpayers who reinvest realized capital gains into Qualified Opportunity Funds (QOF), which in turn invest in designated Opportunity Zones.
Under the One Big Beautiful Bill Act (OBBBA) signed by President Trump—the Opportunity Zone program was made permanent and modernized to support long-term and targeted investment. Investors may benefit from the deferral of capital gains and additional tax advantages tied to the duration of their investment, encouraging sustained capital formation in underserved communities.
Opportunity Zones 2.0
The One, Big, Beautiful Bill Act (OBBBA) was signed into law on July 4, 2025, making the Opportunity Zone program permanent. Under the updated law, Opportunity Zones will be redesignated every 10 years, and several aspects of the program’s requirements and incentives have been revised.
As a result of these updated requirements, not all currently designated Opportunity Zones qualify under the revised eligibility criteria. It was important for states to identify priority areas for inclusion in the new round of designations.
Under federal guidance, governors were provided a window, which began July 1, 2026,to submit Opportunity Zone nominations to the U.S. Department of the Treasury. Each governor is allowed to nominate up to 25% of the state’s eligible census tracts for Opportunity Zone designation. In an effort to support Governor McMaster in his efforts to ensure the state’s nominations reflect local priorities, SC Commerce engaged local governments, economic development organizations, community leaders, and the public at large to provide input.
Census tracts selected
Governor McMaster submitted his nominations for Opportunity Zones to the US Treasury on September 23, 2026, and revised on October 20, 2026. The US Treasury approved the 113 tracts on October 29, 2026, and the new Ozs will go into effect on January 1, 2027.
Changes under OBBBA
The OBBBA introduces several updates to the Opportunity Zone program:
- Makes the Opportunity Zone program permanent and requires that OZs be redesignated every 10 years.
- Establishes new reporting requirements for Qualified Opportunity Funds and directs the U.S. Treasury to publish annual reports on Opportunity Zone investment activity and outcomes, increasing transparency around the program’s impact.
- Provides a new incentive structure, including a five-year rolling deferral beginning on the date of investment and a 10 percent step-up in basis for investments held for five years.
- Updates eligibility criteria by defining low-income communities as census tracts that meet either:
- A median family income below 70 percent of the applicable state or metropolitan median or
- A poverty rate of at least 20 percent and a median family income below 125 percent of the applicable median.
- Eliminates the “contiguous tracts” exception from the first iteration of the program.
- Updates eligibility criteria by defining low-income communities as census tracts that meet either:
- Enhances the incentive for investment in rural Opportunity Zones
- Defines a rural area as any area other than:
- A city or town with a population of greater than 50,000 and
- An urbanized area adjacent to a city or town with a population in excess of 50,000.
- Defines a rural area as any area other than:
NOTE: Review the IRS Notice 2025-50 for more information on the definition released by the U.S. Treasury.
- Provides a 30 percent step-up benefit for investments in a rural Opportunity Zone.
- Reduces the substantial improvement threshold for qualifying projects in rural Opportunity Zones from 100 to 50 percent.
Opportunity Zone participation overview
Opportunity Zones create a framework for businesses, communities and investors to work together to encourage economic growth and attract private investment to designated areas.
*OZ requirements are established under federal law and may be subject to additional US Department of the Treasury and IRS guidance.
For businesses
Businesses located in an OZ may be eligible to receive investment through a Qualified Opportunity Fund (QOF) if they meet federal requirements for a Qualified Opportunity Zone (QOZ) Business.
For communities
States and local communities can use OZs to attract private investment, catalyze redevelopment in distressed or underutilized areas, support job creation and tax base growth, and complement existing incentives to improve overall competitiveness.
For investors
Investors do not need to live, work or operate a business in an OZ to participate in the program. Eligible taxpayers may invest qualifying gains through a QOF and receive federal tax benefits when applicable requirements are met.
Upcoming & recent engagement opportunities
Recorded May 21, 2026
Opportunity Zone webinar
Watch SC Commerce's Opportunity Zone webinar for an overview of program changes, updated eligibility requirements and South Carolina's 2026 nomination process.
How Opportunity Zones work
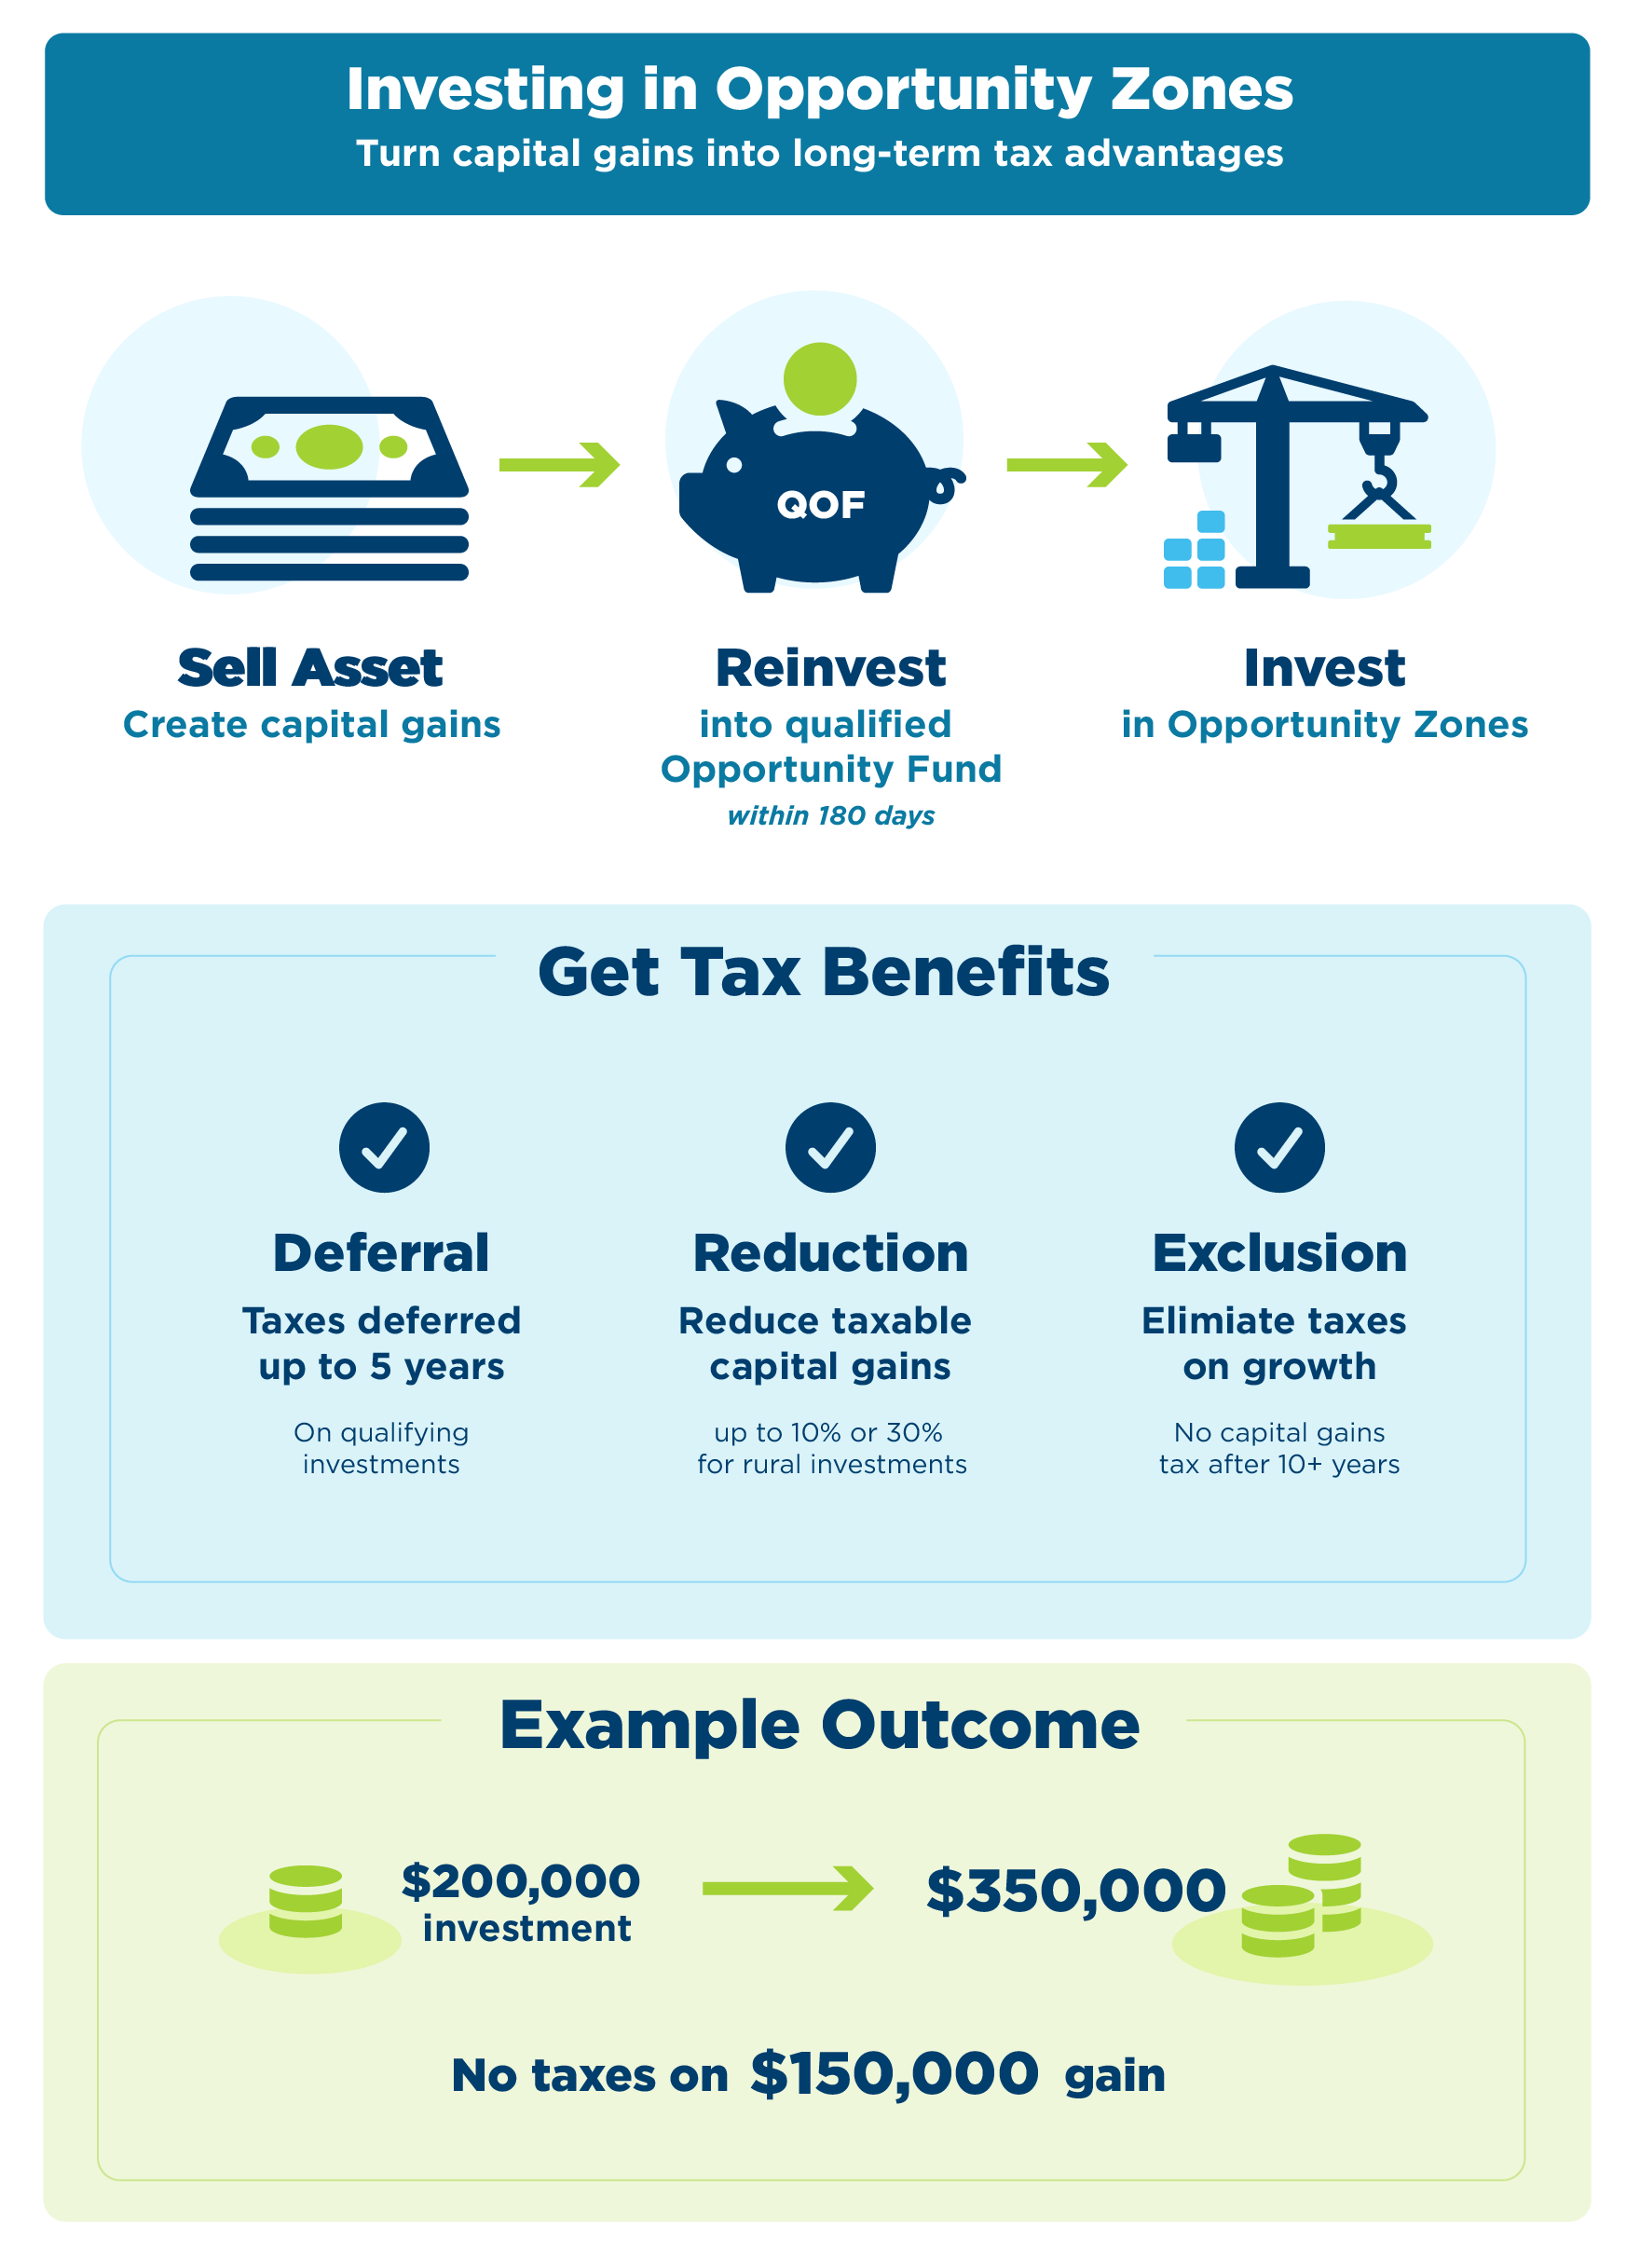
- Step 1: Realize an Eligible Gain: An investor realizes an eligible gain from the sale or exchange of an asset, such as stocks, real estate or business property.
- Step 2: Invest in a QOF: Generally, within 180 days, the investor invests an amount corresponding to the eligible gain in a QOF.
- Step 3: Invest in QOZs: The QOF invests in qualifying property or businesses located within QOZs.
- Step 4: Receive Potential Tax Benefits: For qualifying investments made beginning January 1, 2027:
- Deferral: Tax on the eligible gain may generally be deferred for up to five years from the date of the QOF investment.
- Basis increase: A qualifying QOF investment held for at least five years generally receives a 10% basis increase. Qualifying investments in a Qualified Rural Opportunity Fund may receive a 30% basis increase.
- Long-term benefit: Investors who hold a qualifying QOF investment for at least 10 years may be eligible to exclude appreciation on the QOF investment from federal income tax, subject to applicable federal requirements.
South Carolina Opportunity Zones interactive map
The map below shows census tracts nominated by Governor McMaster to be designated as Qualified Opportunity Zones and approved by the U.S. Treasury. The new Opportunity Zones will go into effect January 1, 2027.
Click the map to open an interactive view of the opportunity zones submitted by Governor McMaster and approved by the US Treasury.
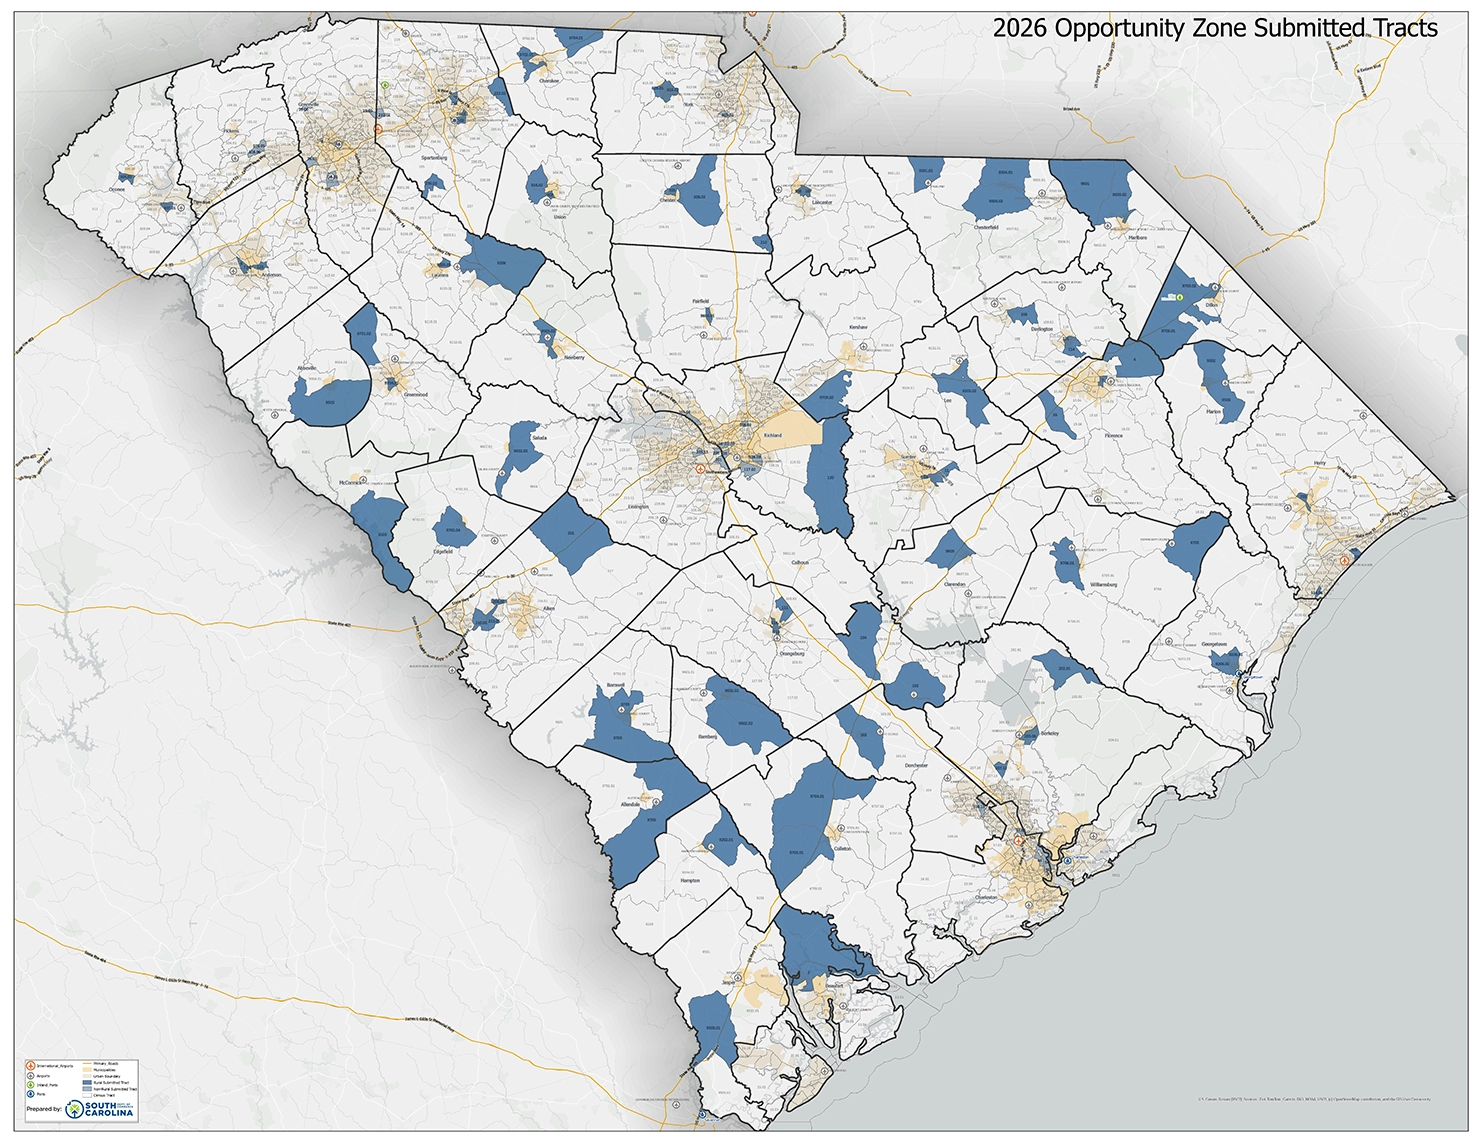
The map below reflects Opportunity Zone designations approved in 2018 and does not represent future designations. Areas marked in blue represent current Opportunity Zones that were designated in 2018 and will only be effective until the end of 2026. When using the search tool, you may need to zoom out to determine whether a location falls within a highlighted zone.
* This address locator is provided as a service to help potential investors determine the likelihood that a particular address falls within an Opportunity Zone. It is not meant to provide a definitive judgement on the qualification of a particular address and should not be used as such. It is advised that all prospective participants in the Opportunity Zone program consult the County of record for a more detailed analysis of the parcel in question as well as evaluate the regulations put forth by the US Department of the Treasury.
Download a PDF of the 2018 Opportunity Zone census tracts (not 2027 designations).

