Opportunity Zones
The Opportunity Zone (OZ) program is a federal initiative designed to encourage economic development and job creation through long-term private investment in designated low-income urban and rural communities.
Program background
Originally enacted as part of the Tax Cuts and Jobs Act of 2017, the OZ program provides federal tax incentives for taxpayers who reinvest realized capital gains into Qualified Opportunity Funds (QOF), which in turn invest in designated OZs.
Under the One Big Beautiful Bill Act (OBBBA) signed by President Trump—the OZ program was made permanent and modernized to support long-term and targeted investment. Investors may benefit from the deferral of capital gains and additional tax advantages tied to the duration of their investment, encouraging sustained capital formation in underserved communities.
Opportunity Zones 2.0
The One Big Beautiful Bill Act (OBBBA) was signed into law on July 4, 2025, making the Opportunity Zone program permanent. Under the updated law, OZs will be redesignated every 10 years, and several aspects of the program’s eligibility requirements and incentives have been revised.
As a result of these changes, not all currently designated OZs are eligible for redesignation under the revised criteria. The redesignation process gives states an opportunity to identify priority areas for inclusion in the next round of OZ designations.
The federal nomination window opened July 1, 2026, allowing governors to submit OZ nominations to the US Department of the Treasury. In South Carolina, SC Commerce is supporting Governor McMaster in the process of identifying and nominating up to 25% of the state’s eligible census tracts for OZ designation.
As part of this process, SC Commerce is engaging with local governments, economic development organizations, community leaders and members of the public to help ensure the state’s nominations reflect local priorities.
Changes Under OBBBA
The OBBBA introduces several significant changes to the Opportunity Zone program:
- Makes the OZ program permanent and requires OZs to be redesignated every 10 years.
- Establishes new reporting requirements for QOFs and directs the US Department of the Treasury to publish annual reports on OZ investment activity and outcomes, increasing transparency around the program’s impact.
- Updates eligibility criteria for low-income communities. Under the revised criteria, qualifying census tracts must meet certain income or poverty thresholds.
- Eliminates the “contiguous tracts” exception included in the original OZ program.
- Establishes a new incentive structure for investments made beginning January 1, 2027, including:
- A rolling five-year deferral period beginning on the date of investment.
- A 10% step-up in basis for qualifying investments held for at least five years.
- Enhances incentives for investment in rural OZs. Under the updated law:
- A rural area is generally defined as an area other than a city or town with a population greater than 50,000 or an urbanized area contiguous and adjacent to such a city or town.
- Qualifying investments in rural Opportunity Funds made beginning January 1, 2027, may receive a 30% step-up in basis after five years.
- The substantial improvement threshold for qualifying property located entirely within a rural OZ has been reduced from 100% to 50%. This change took effect July 4, 2025.
Review IRS Notice 2025-50 for additional guidance on rural OZs and the substantial improvement requirement.
Opportunity Zone participation overview
Opportunity Zones create a framework for businesses, communities and investors to work together to encourage economic growth and attract private investment to designated areas.
*OZ requirements are established under federal law and may be subject to additional US Department of the Treasury and IRS guidance.
For businesses
Businesses located in an OZ may be eligible to receive investment through a Qualified Opportunity Fund (QOF) if they meet federal requirements for a Qualified Opportunity Zone (QOZ) Business.
For communities
States and local communities can use OZs to attract private investment, catalyze redevelopment in distressed or underutilized areas, support job creation and tax base growth, and complement existing incentives to improve overall competitiveness.
For investors
Investors do not need to live, work or operate a business in an OZ to participate in the program. Eligible taxpayers may invest qualifying gains through a QOF and receive federal tax benefits when applicable requirements are met.
Recorded May 21, 2026
Opportunity Zone webinar
Watch SC Commerce's Opportunity Zone webinar for an overview of program changes, updated eligibility requirements and South Carolina's 2026 nomination process.
Timeline for South Carolina Opportunity Zone selection
April – June 2026
Community Nomination Period – Complete
SC Commerce invited local governments and economic development organizations across South Carolina to recommend eligible census tracts for consideration. The community nomination period closed June 15, 2026.
June – July 2026
Review and Recommendation – Complete
SC Commerce reviewed community nominations alongside relevant economic, infrastructure and investment data to develop recommendations for the Governor’s consideration.
July – December 2026
Governor Review and Nomination
The Governor and his team are reviewing recommended census tracts to determine South Carolina’s final nominations for OZ designation. Final nominations will be submitted to the US Department of the Treasury.
January 2027
New Opportunity Zones Take Effect
The newly designated OZs take effect January 1, 2027.
How Opportunity Zones Work
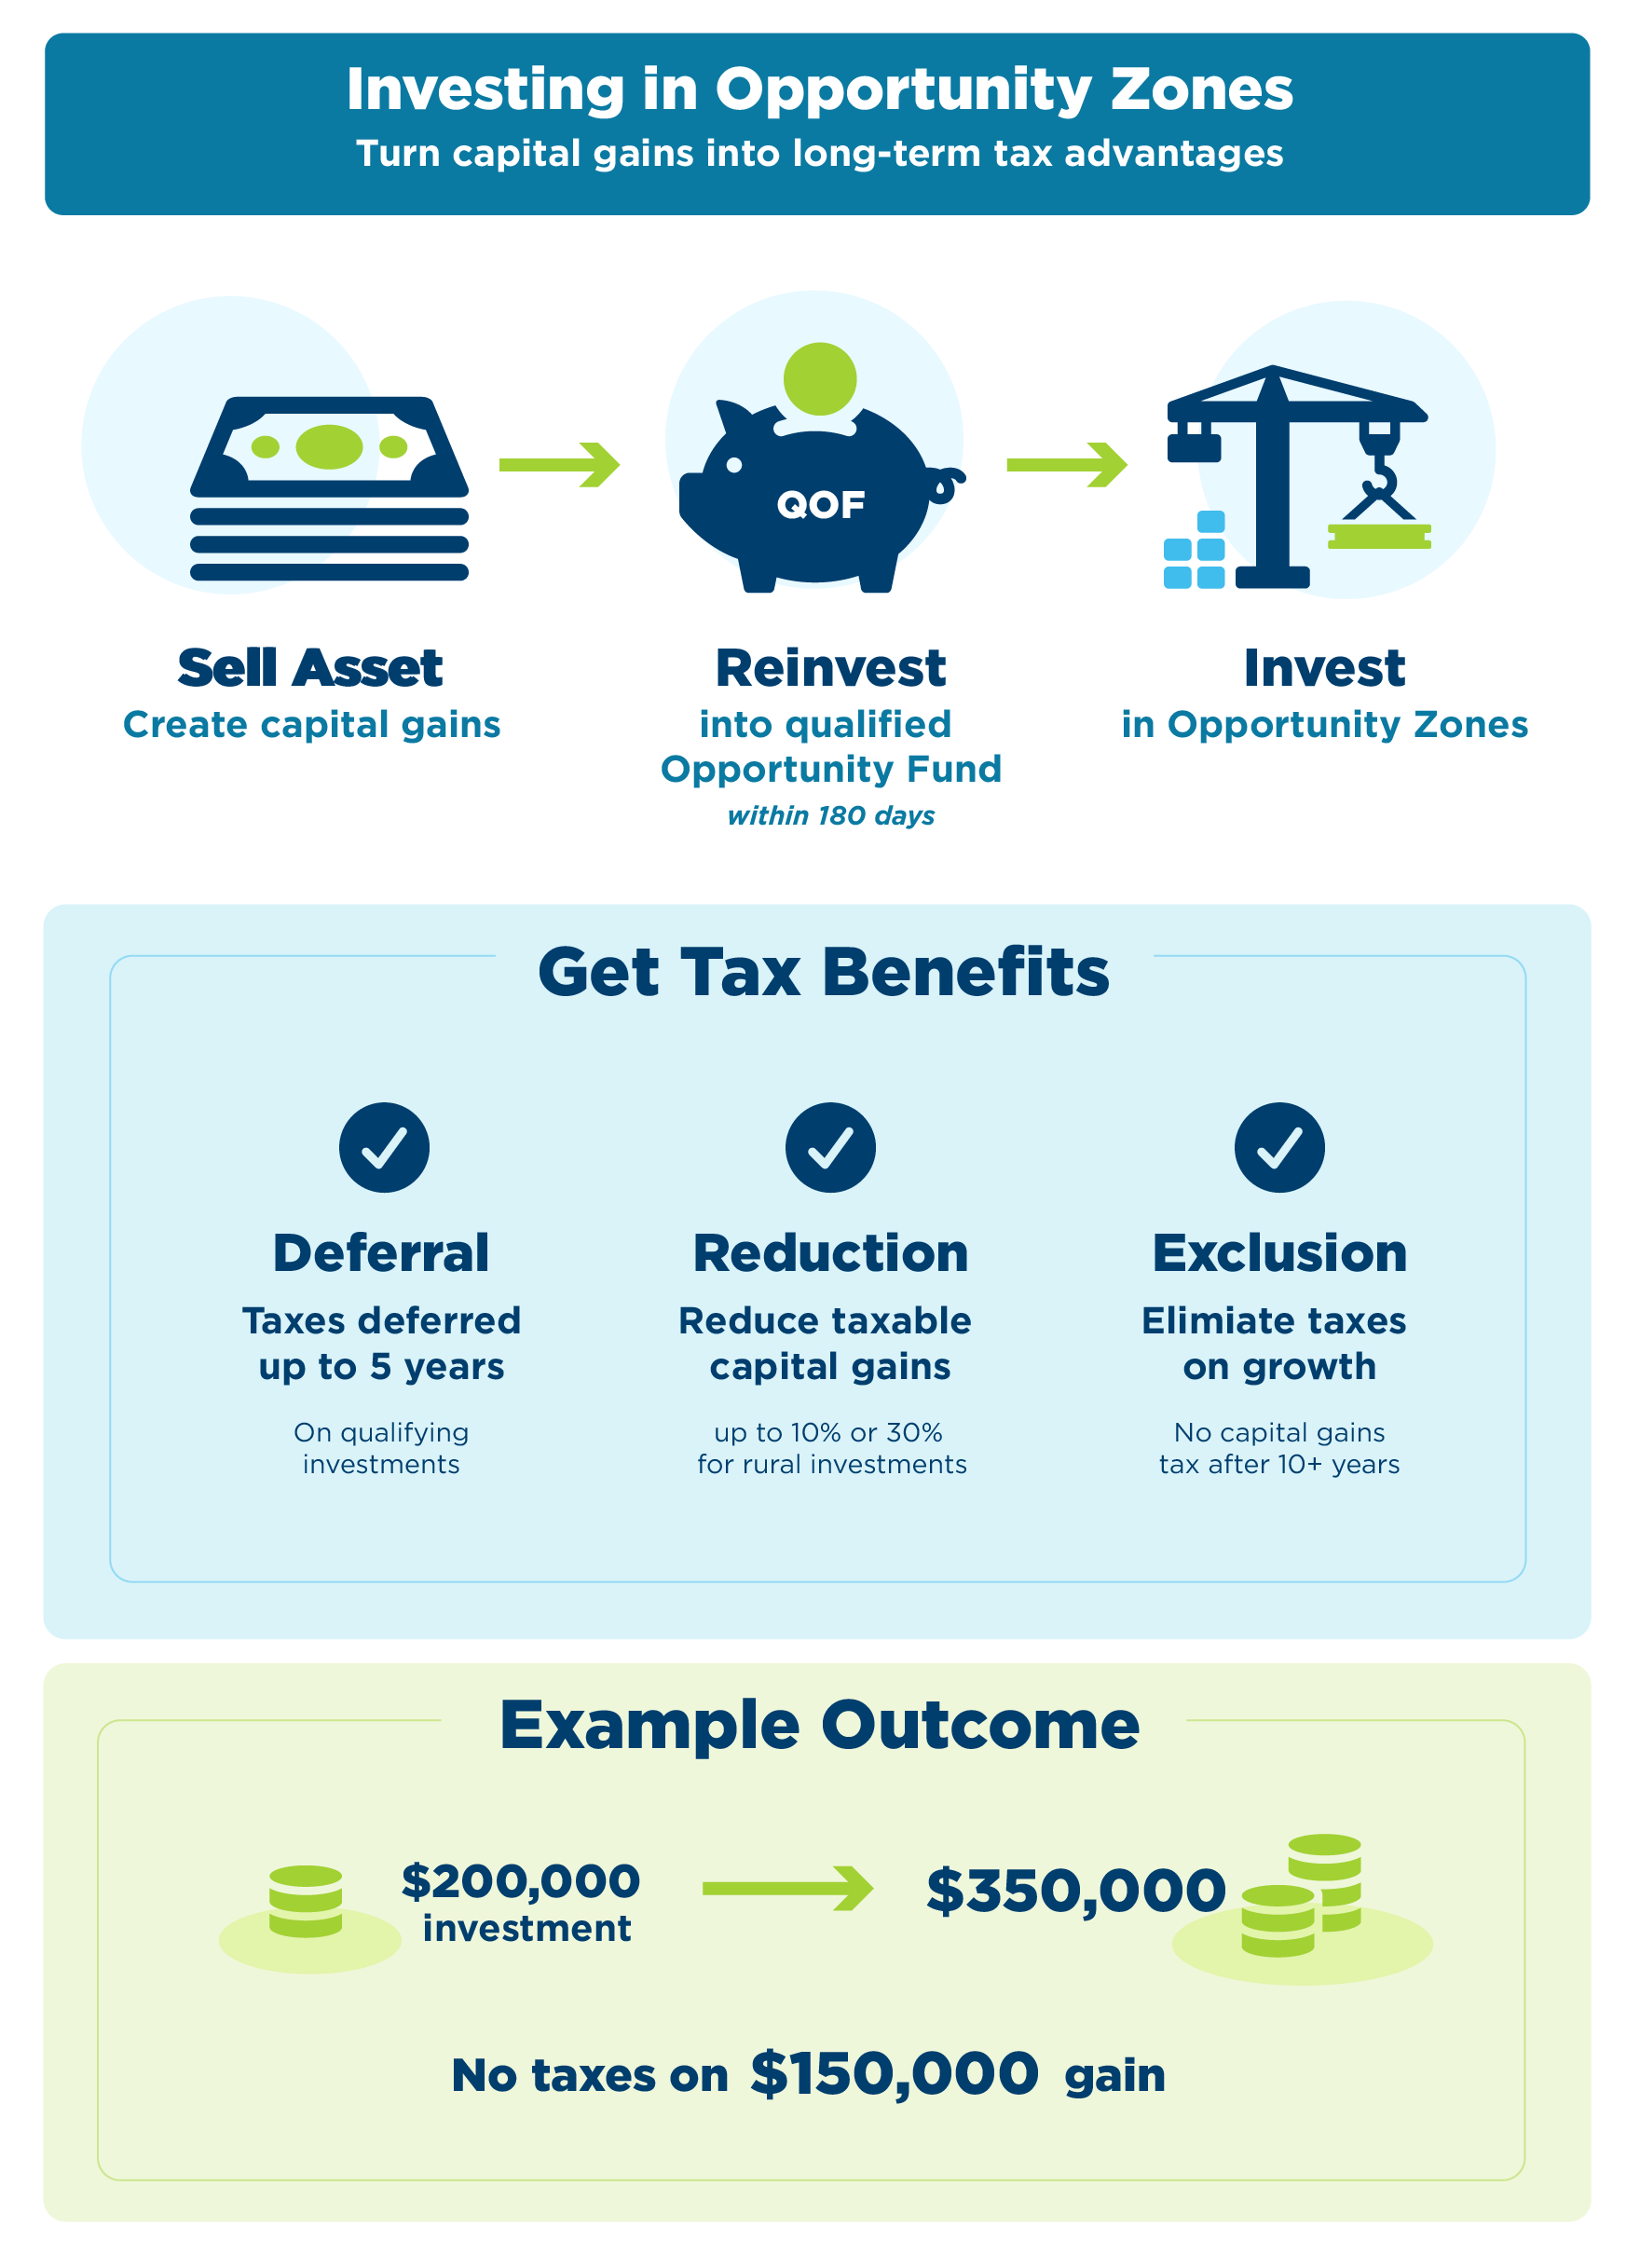
- Step 1: Realize an Eligible Gain: An investor realizes an eligible gain from the sale or exchange of an asset, such as stocks, real estate or business property.
- Step 2: Invest in a QOF: Generally, within 180 days, the investor invests an amount corresponding to the eligible gain in a QOF.
- Step 3: Invest in QOZs: The QOF invests in qualifying property or businesses located within QOZs.
- Step 4: Receive Potential Tax Benefits: For qualifying investments made beginning January 1, 2027:
- Deferral: Tax on the eligible gain may generally be deferred for up to five years from the date of the QOF investment.
- Basis increase: A qualifying QOF investment held for at least five years generally receives a 10% basis increase. Qualifying investments in a Qualified Rural Opportunity Fund may receive a 30% basis increase.
- Long-term benefit: Investors who hold a qualifying QOF investment for at least 10 years may be eligible to exclude appreciation on the QOF investment from federal income tax, subject to applicable federal requirements.
South Carolina Opportunity Zones Interactive Map
The map below reflects Opportunity Zone designations approved in 2018 and does not represent current or future designations. Areas marked in blue represent current Opportunity Zones that were designated in 2018. When using the search tool, you may need to zoom out to determine whether a location falls within a highlighted zone.
This map reflects Opportunity Zone designations approved in 2018 and does not represent current or future designations.
* This address locator is provided as a service to help potential investors determine the likelihood that a particular address falls within an Opportunity Zone. It is not meant to provide a definitive judgement on the qualification of a particular address and should not be used as such. It is advised that all prospective participants in the Opportunity Zone program consult the County of record for a more detailed analysis of the parcel in question as well as evaluate the regulations put forth by the US Department of the Treasury.
Download a PDF of the 2018 Opportunity Zone census tracts (not current designations).
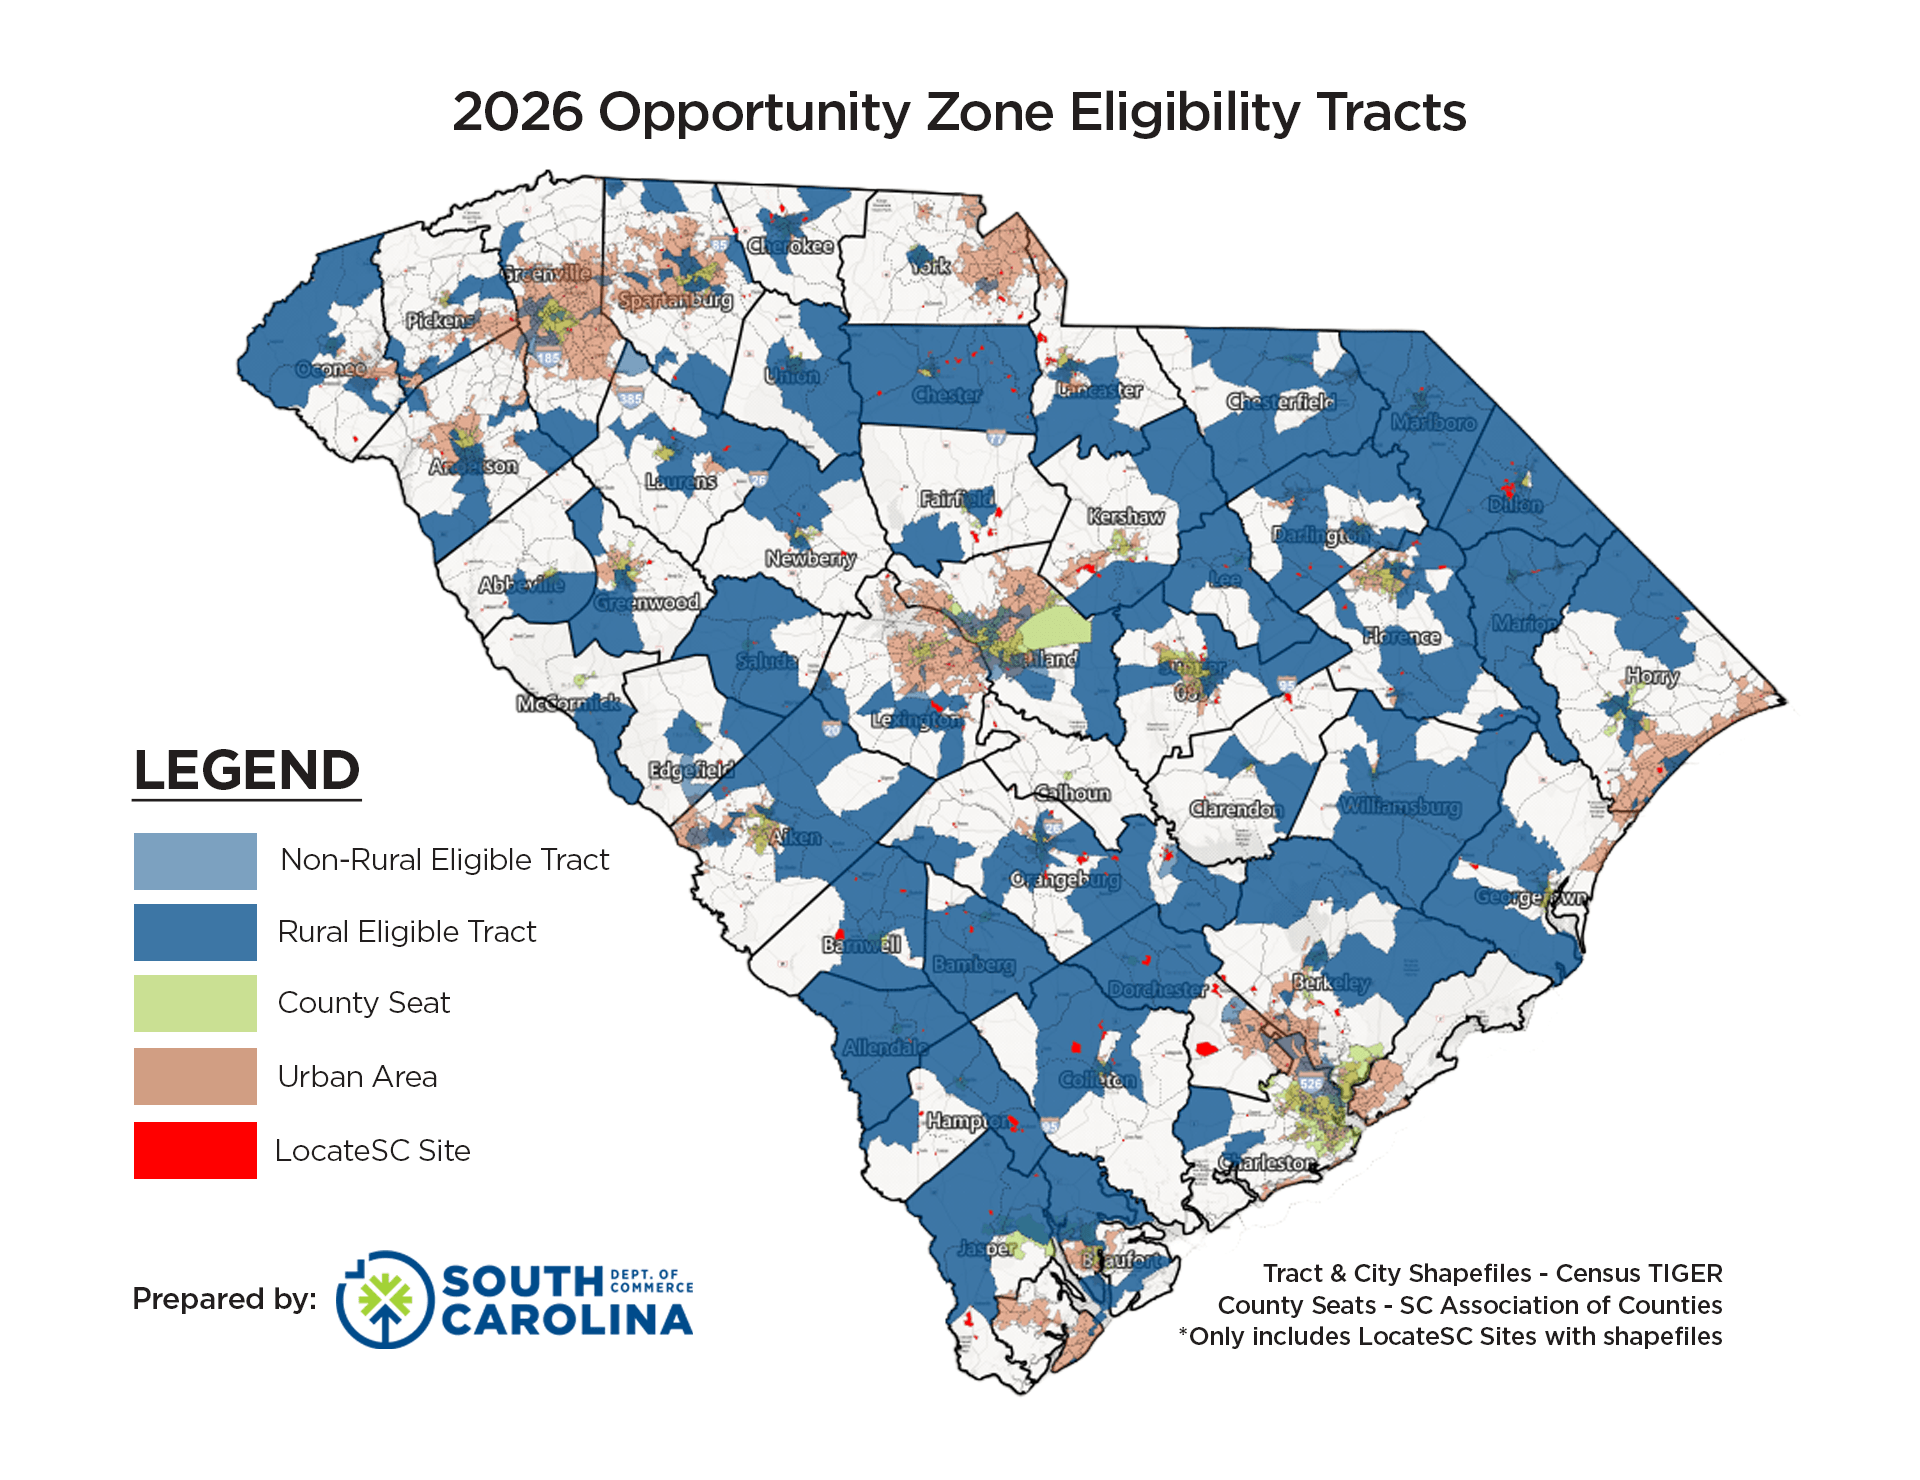
The map below shows census tracts eligible for consideration for Opportunity Zone designation as determined by the US Treasury. See https://www.irs.gov/pub/irs-drop/rp-26-14.pdf. Please note that not all of these eligible tracts will be designated as Qualified Opportunity Zones. The Governor may only designate up to 25% of the eligible tracts.